News · Baillie Gifford US Growth Trust plc · Scottish Mortgage Investment Trust PLC
Zipline doubles in Scottish Mortgage and US Growth: what the revaluation changes for shareholders
The autonomous-drone maker now accounts for 3.8% and 4.0% of the two trusts. The NAV uplift is real, but it creates neither immediate cash nor a guaranteed exit price.
Within weeks, Zipline has gone from an interesting private holding to an asset capable of visibly moving the value of two listed trusts. On 17 September, Scottish Mortgage and Baillie Gifford US Growth announced an increase in its valuation. Zipline now represents 3.8% of the former's assets and 4.0% of the latter's, roughly twice the proportions reported at 31 July.
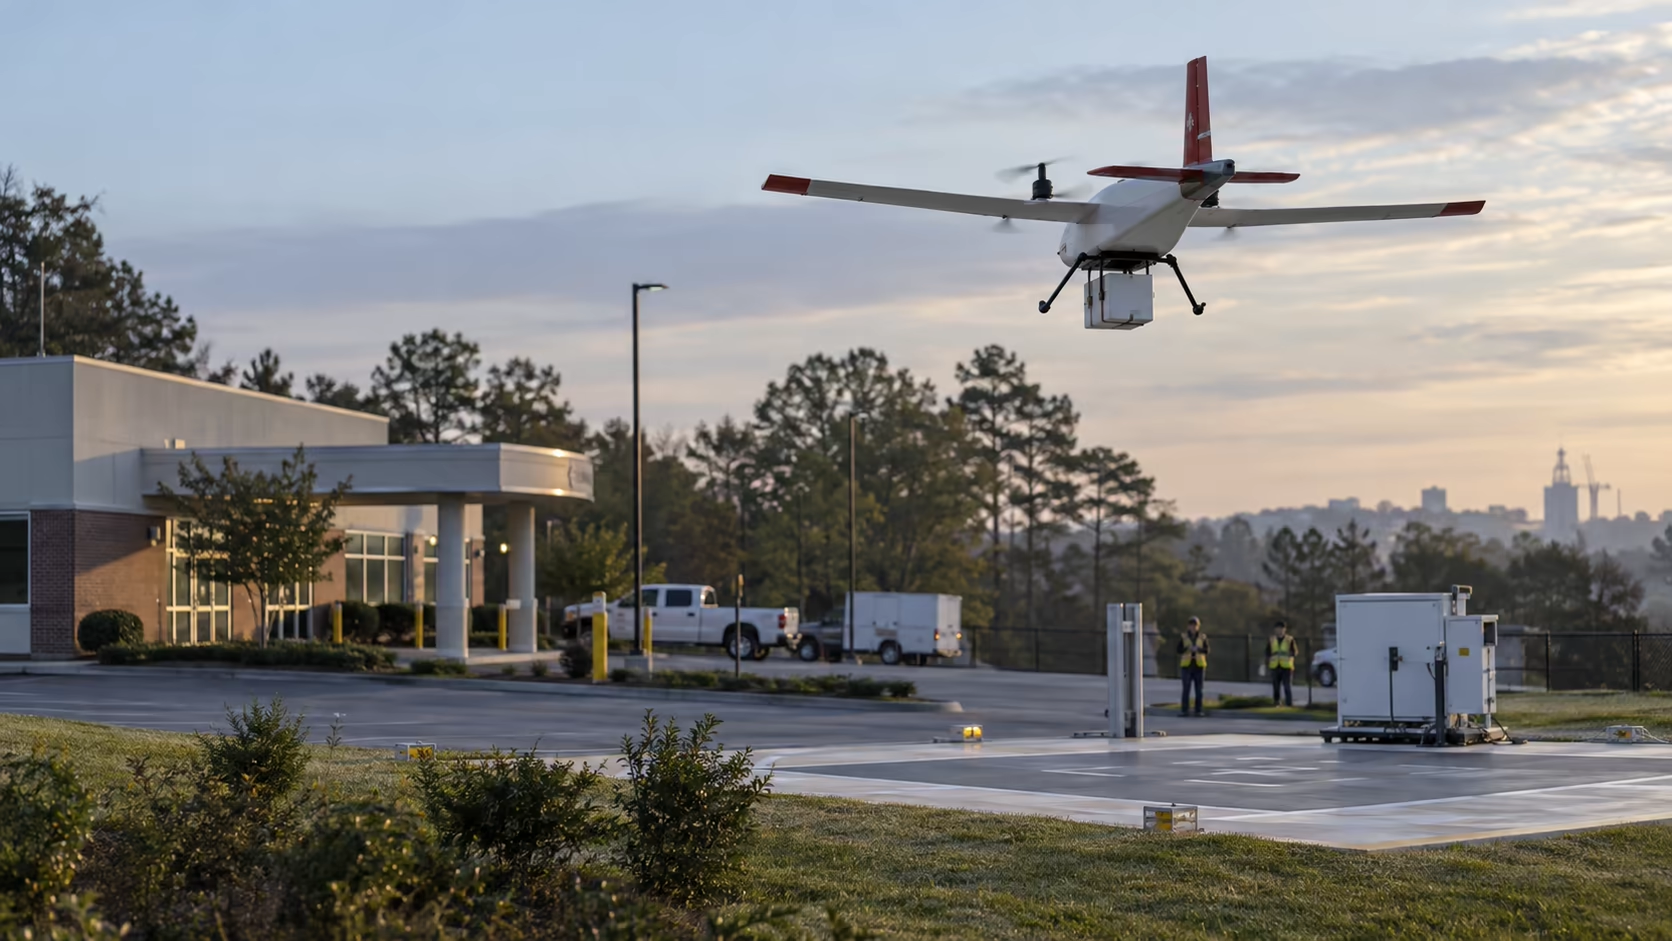
First, what does Zipline actually do?
Zipline designs, manufactures and operates autonomous drones. The company first became known for delivering blood, vaccines and medicines to hard-to-reach hospitals, particularly in Africa. It is now trying to convert that operating experience into a fast US delivery infrastructure for prescriptions, meals and everyday purchases.
The change in scale is visible. Zipline reported more than 2.5 million commercial deliveries in July, including one million over the previous twelve months. In August, Uber announced a strategic investment and a partnership with a long-term target of one million deliveries per day. These are company ambitions, not yet evidence of profitability.
The model remains capital-intensive. Zipline is not merely selling software: it manufactures aircraft, installs stations, secures regulatory approvals, maintains the fleet and opens each service area. Value therefore depends on both the quality of the technology and the ability to drive down the cost per delivery as volumes rise.
What changed on 17 September
Both boards issued an unusual regulatory update: the manager had raised Zipline's value under its private-company valuation policy, and the effect on NAV was material enough to warrant immediate disclosure.
Specialist press reports connect the adjustment with talks over a roughly $1bn raise that could value Zipline at about $20bn. In January, Zipline itself announced more than $600m of funding at a $7.6bn valuation. The new round must not be described as completed: the trusts' primary filings confirm the revaluation of their securities, not the final funding terms.
This distinction helps explain why the portfolio weights roughly doubled while $20bn is more than two and a half times January's figure. The trusts may own several security classes with different rights; the new round's terms, movements in the rest of the portfolio and exchange rates also matter.
Turning percentages into pounds
Percentages can feel abstract. Using the rounded asset sizes published by the Association of Investment Companies, 3.8% of a Scottish Mortgage portfolio close to £16bn represents roughly £600m. Four per cent of a US Growth portfolio close to £1bn represents roughly £40m.
Approximate scale
Opulion estimate: 3.8% applied to roughly £16bn of assets. This is not an audited line value at 16 September.
Approximate scale
Opulion estimate: 4.0% applied to roughly £1bn of assets. The exact amount depends on daily assets.
These orders of magnitude explain why the announcement matters. A holding of this size can lift NAV without the trust buying another share. It can also work in reverse if the next market reference is lower.
A valuation gain is not a cash inflow
NAV, or portfolio value after debt, combines listed assets at quoted prices and private assets at estimated fair value. Zipline has no continuously traded public share price. The manager therefore relies on funding rounds, comparable transactions, operating performance and the rights attached to each security.
- 1A new reference appearsA funding round or transaction provides a recent price for certain Zipline securities.
- 2The manager revalues the holdingShare rights, dilution and operating information are incorporated under the fair-value policy.
- 3Trust NAV increasesPublished value per share rises even though no Zipline shares have been sold.
- 4The market sets the share priceThe trust can still trade at a discount or premium to that NAV.
The first benefit to shareholders is measurable: the new estimate is already included in published NAV, at 1,648.93p for Scottish Mortgage and 372.15p for US Growth on 16 September. The second benefit remains potential: a sale, flotation or future distributions could eventually turn that value into cash.
The same asset creates two different shareholder questions
Scottish Mortgage: a private success becomes more material
Scottish Mortgage runs a portfolio of about £16bn across listed and private companies. Private investments represented roughly 20% of assets at 30 June. At 3.8%, Zipline is now large enough to influence performance, although it remains well below SpaceX's concentration.
The upside is clear if Zipline builds a profitable global network. So is the risk: the trust is more exposed to an unobservable estimate, and a large block cannot be guaranteed to sell at the value carried in NAV.
US Growth: the revaluation meets the liquidity debate
Zipline now accounts for 4.0% of US Growth, while private companies already represented 42.9% of assets in the May factsheet. This is deliberate: the trust seeks access to exceptional growth companies before flotation.
But it directly intersects with the dispute involving Saba Capital. The board has disclosed that it offered a cash exit near 99.75% of NAV, which it says Saba rejected. Our previous article explained that the question is not only the offered price, but how to fund an exit without distorting the remaining portfolio.
Zipline's increase strengthens both sides of the argument. It raises the NAV shareholders might want to realise. It also increases the portion of that NAV that cannot be sold instantly in a public market. Higher value is therefore not automatically easier liquidity.
What the new valuation does not prove
It does not prove that Zipline is already worth $20bn for every investor. The financing is still reported as being under discussion. New preferred shares may carry protections that older securities do not. Deployment costs, airspace regulation, noise, weather and unit economics remain critical variables.
Nor does it prove that the stock market will accept published NAV at face value. Investors may apply a discount for illiquidity, uncertainty around private valuations and the future cost of building the network.
Opulion view
Zipline is a textbook case of how a private company can create substantial value inside a listed trust before producing any cash for that trust. For Scottish Mortgage, the revaluation makes an industrial success more visible within a very large portfolio. For US Growth, it makes the tension between access to leading private companies and liquidity for shareholders even more concrete.
The next important number will not be the headline valuation alone. Investors should watch the amount actually raised, the rights attached to new securities, delivery growth, economics in each new market and the trusts' ability to sell part of their holdings. Only then will accounting value begin, or fail, to converge with realisable value.
Sources
- Scottish Mortgage, regulatory NAV and Zipline valuation update, 17 September 2026
- Baillie Gifford US Growth, regulatory NAV and Zipline valuation update, 17 September 2026
- Zipline, more than $600m raised at a $7.6bn valuation, 21 January 2026
- Zipline, US expansion and 2.5 million deliveries, 14 July 2026
- Zipline, Uber partnership and strategic investment, 17 August 2026
- Association of Investment Companies, summary of the uplift and reported financing, 18 September 2026
- Baillie Gifford, private-company valuation approach
Share this piece