News · Wendel SE
Wendel: Stahl cuts net debt to €183m, but adjusted net debt under S&P's method rises to €714m
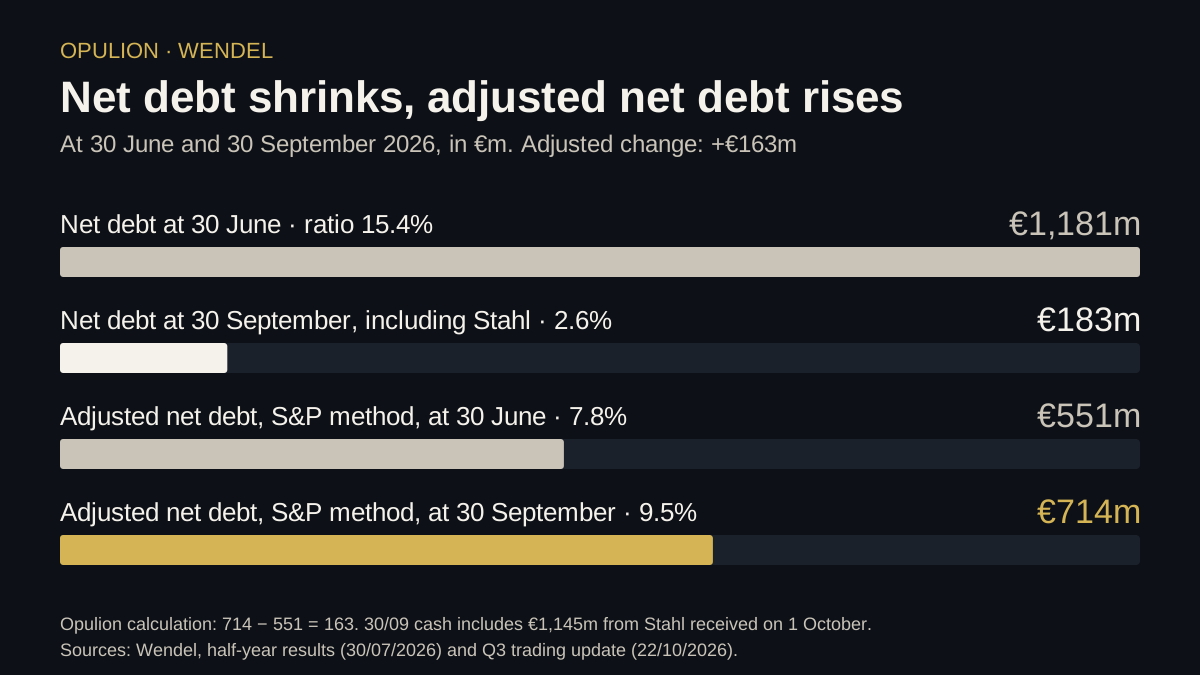
At 30 September 2026, Wendel's net debt falls to €183m, from €1,181m in June, because its cash already includes the €1,145m from Stahl received on 1 October. The loan-to-value ratio under S&P's method, which had counted upcoming disposals since June, nevertheless rises from 7.8% to 9.5%. Using the same method, adjusted net debt rose by €163m in one quarter, to €714m.
Why it matters for Wendel shareholders: the net asset value published the same day rises to €167.0 per share at 30 September, from €158.9 at 30 June. That figure measures value. Adjusted net debt measures room for manoeuvre, in reverse: by how much debt, puts and fund commitments exceed cash and expected transactions. Stahl changed the shape of Wendel's balance sheet, and its room for manoeuvre shrank over the quarter.
Wendel publishes two leverage ratios (loan-to-value), as our analysis of 21 September explained. The "spot" ratio divides net debt by assets: 15.4% in June, 2.6% in September, Stahl included. The ratio under S&P's method divides adjusted net debt by assets corrected for the same restatements: €551m over €7,058m in June, €714m over €7,506m in September (Opulion calculation). In June, its restatements counted €1,546m of post-closing disposals and acquisitions, share buyback included, a line that included Stahl and IHS on our reading, with Wendel then expecting around €1.65bn from the two. In September, the same line falls to €414m, with no published breakdown. The fall in the spot ratio comes from Stahl, and only the ratio under S&P's method compares the two quarters using the same method. Our article of 5 October warned that October's cash cannot be attached to the June balance sheet. Wendel attaches it to the September balance sheet, under an explicit label.
Opulion calculation: the resources used by the method, cash at the reporting date plus post-closing transactions, fall from €2,053m (507 + 1,546) to €1,914m (1,500 + 414), €139m less. Puts rise by €26m, uncalled commitments by €1m, and debt falls by €4m. The total comes to €162m: the sums reconcile to within €1m, the gap coming from the issuer's rounding. The release discloses a single use of cash in the quarter, €50m reinvested in Globeducate in September. The amount counted for Stahl in the June line remains unknown: Wendel expected around €1.2bn in July, and received €1,145m.
Puts and commitments are possible or promised cash outflows in exchange for assets, not losses of value. The puts, €550m, are the put options linked to Monroe Capital and Committed Advisors, in which Wendel holds around 72% and 64%. For Monroe, the closing release of 31 March 2025 provided for a put and a call on the 25% retained by the sellers, in three instalments from 2028 to 2032, payable in cash. The €394m of uncalled commitments are owed to the funds of IK Partners, Monroe, Committed Advisors and Iron Wave, as capital is called. The net asset value of €167.0 per share counts the stake held in each manager, without deducting these amounts.
The shape
A signed disposal becomes cash, which the ratio under S&P's method had counted since June, on our reading.
Resources
Cash and post-closing transactions, as used by the method, over the quarter.
Puts and funds
€550m of puts and €394m of uncalled commitments at 30 September, versus €917m in June.
For Wendel shareholders, three facts will settle the matter by year-end: payment of the €2.55 per share interim dividend on 19 November, around €98m (Opulion calculation on the 38.6 million shares used for net asset value per share at 30 September), the investor day on 2 December, then the closing of the IHS disposal, expected by year-end for around $535m if IHS shareholders and the authorities approve it. The fourth will take longer: the use of the €1,500m of cash at 30 September, Stahl included, against which the ratio under S&P's method already counts €944m of puts and commitments.
Sources
- Wendel, completion of the acquisition of a controlling stake in Monroe Capital, 31/03/2025 · Wendel · Mar 31, 2025
- Wendel, Q3 2026 trading update (NAV at 30/09, appendices 1 and 2), 22/10/2026 · Wendel · Oct 22, 2026
- Wendel, 2026 half-year results (appendix 3, LTV at 30/06), 30/07/2026 · Wendel · Jul 30, 2026
Share this article