News · Groupe Bruxelles Lambert SA
GBL and Recordati: persuading sellers now comes at a higher price
The offer seeks all available shares at €53. A 12 October dashboard separates acceptances, physical holdings and conditional delivery under CVC’s contract.
An investment holding company needs both funding and willing sellers to complete an acquisition. Raising the price may help secure the deal, but it also leaves the business with more capital to earn a return on. GBL’s involvement in the Recordati offer makes that trade-off tangible.
On 6 October, the consortium including GBL raised its offer for the Italian drugmaker from €51.29 to €53 a share and extended it to 23 October. By 12 October, total acceptances had reached 100.04 million shares. CVC’s market purchases are also moving the consortium forward, although a gap remains to the stated 66.67% threshold.
Progress now needs to be measured through acceptances and market purchases together. Two questions matter: how many more shares are needed, and how much capital will GBL ultimately commit?
Rossini is selling. A new team is buying
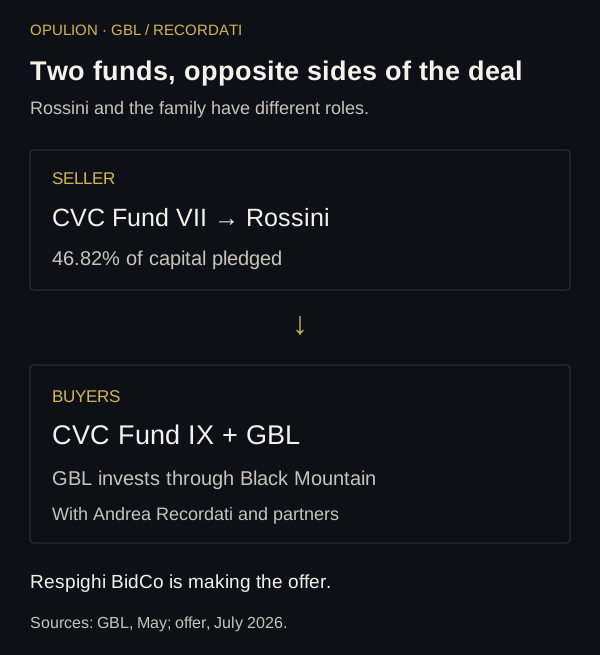
Rossini holds the large Recordati block, representing 46.82% of share capital. The vehicle belongs to CVC Fund VII and has already tendered its 97,912,463 shares, according to the 12 October announcement.
On the buying side are CVC Fund IX and GBL, alongside their partners. Black Mountain is GBL’s investment vehicle for the transaction. Andrea Recordati, a member of the drugmaker’s founding family, is also taking part in the new ownership structure. The family and Rossini have different roles.
Why are two CVC funds involved? An older fund can sell an investment to a newer fund alongside fresh partners. Capital changes hands. GBL shareholders need to assess what the incoming owners can achieve with Recordati at the price paid.
€53 to receive, €53.71 for comparison
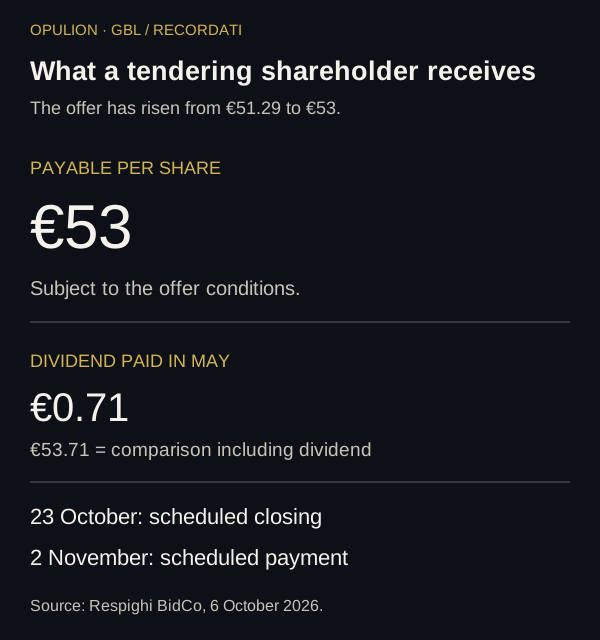
A shareholder tendering a share now will receive €53 under the offer terms. The announcement also cites €53.71. That figure includes the €0.71 dividend paid in May and compares the total received by a shareholder who held the share through that distribution.
The €1.71 increase is 3.33% above the previous offer price. Across all shares covered by the offer, it adds approximately €339.5m to the maximum consideration, bringing it to €10.52bn. That is the consortium’s envelope. The announcement does not detail GBL’s additional contribution.
Where does the consortium stand on 12 October?
The offer aims to acquire all available shares and take Recordati private. Its reference scope covers 198.53 million shares, or 94.93% of share capital. Shares already held directly by GBL and CVC sit outside that offer base and must be added separately when tracking the threshold.
By 12 October, 100,040,791 shares had been tendered, or 50.39% of the shares covered by the offer. Against Recordati's total 209,125,156 shares, the same acceptances represent 47.84%. Changing the denominator changes the picture.
That evening's original announcement also disclosed 6,793,019 physical shares held by CVC and 6,800,946 held by Black Mountain, GBL's vehicle. Adding them to acceptances produces 54.34% of share capital. This is a reconstruction of shares held or tendered before settlement, rather than ownership already transferred to Respighi.
CVC also has a contract with UniCredit, known as a total return swap, covering 10.25 million shares. Full physical delivery would lift the total to 59.24%. The 12 October announcement still reports this as a financial instrument separate from physical holdings. We therefore show it separately.

Rossini's block dominates the headline tally
Rossini's 97,912,463 shares have already been tendered, as the original announcement now confirms. That block represents 46.82% of share capital. Acceptances beyond the main seller total just 2.13 million shares, or 1.02% of share capital.
There is a second route forward: CVC's market purchases. Its physical holding has risen from the 3.80 million shares disclosed in July to 6.79 million on 12 October, an additional 2.99 million shares. Both channels matter.

Can we measure the likelihood of success?
We can measure the remaining distance. With full delivery under CVC's contract, another 15.54 million shares, or 7.43 percentage points of share capital, are needed to reach 66.67%. Without that delivery, the gap is 25.79 million shares.
Nine trading sessions remain after 12 October before the scheduled close. Gathering 15.54 million shares would require an average of 1.73 million per session, through acceptances and market purchases combined. On 12 October, those channels added 377,567 shares. The comparison shows how much the pace would need to increase. It is no forecast: a large late acceptance could change the tally quickly.
The price was raised on 6 October. Recordati's board unanimously welcomed the increase on 7 October. Its independent directors said the new price fell within the most relevant valuation ranges, including the discounted cash-flow range. That removes an obstacle, while leaving each shareholder free to decide.
The quantitative condition is met
Subject to the other conditions, the consortium can purchase tendered shares. Delisting still requires the steps set out in the offer document.
The bidder may waive the condition
It may proceed with fewer shares. The threshold is therefore not an automatic dividing line between success and failure.
Acquire all shares and take Recordati private
The offer targets the remaining available shares. Reaching two thirds of capital does not mean owning the whole business.
The useful dashboard combines shares gathered, actual contract delivery and any decision to waive the threshold. An acceptance rate cannot mechanically be converted into a probability of success.
What matters to GBL shareholders
Recordati develops and sells medicines, including treatments for rare diseases and specialist care. For the holding company led by Johannes Huth (Ian Gallienne chairs the board), the transaction deepens its investment in healthcare and privately held businesses whose development it can influence.
The original May plan envisaged up to approximately €1.3bn from GBL, including shares already purchased. That was close to 10% of its end-March net asset value. The price has now changed. The key information will be GBL’s final contribution, its rights within the consortium and the returns achievable on the updated investment.
The next milestone is the scheduled 23 October closing. Payment is set for 2 November, with a possible reopening from 3 to 9 November. The 66.67% threshold remains an offer condition that can be waived under its terms. Delisting also depends on further rules and steps.
How we counted
Acceptances come from Teleborsa's 12 October bulletin at 18:27. CVC and GBL's physical holdings, the contract covering 10.25 million shares and Rossini's completed tender come from the original 12 October announcement. Reference share capital is 209,125,156 shares. The acceptance tally uses a published 198,525,562-share offer base, rather than total share capital.
We add 100,040,791 tendered shares, 6,793,019 CVC physical shares and 6,800,946 GBL physical shares without counting Rossini twice. The conditional case adds 10,250,000 separate contract shares. The 66.67% threshold requires at least 139,423,742 shares on this basis. The gaps are 25,788,986 shares without delivery and 15,538,986 with full delivery. The nine remaining sessions exclude 12 October. That day's flow combines 135,724 acceptances and 241,843 CVC purchases. It is no forecast.
Update and correction, 12 October 2026: today's disclosed holdings replace July positions previously assumed unchanged. Our brief described 58.74% as an effective holding on 8 October. That reconstructed figure already included CVC's contract and should not have been treated as physical shares held. The board's welcome dates from 7 October, rather than the 8 October date of some press coverage.
The €1.3bn and 10% refer to the original plan and March NAV. The maximum incremental cost uses all shares in the 6 October offer base. The Italian version prevails.
Correction to our 17 September article: the 16 September tally was 98,281,665 shares. The 98,281,125 quoted belonged to 15 September. The distance to the threshold also needs to include shares held outside the offer. Our analyses of the original offer and its financing provide the background to this update.
Sources
- Respighi BidCo, CVC purchases and exact holdings, 12 October 2026
- Recordati, unanimous board welcome, 7 October 2026
- Respighi BidCo, €53 offer increase, Italian original, 6 October 2026
- Teleborsa, acceptances at 18:27 on 12 October 2026
- GBL, initial investment and healthcare strategy, 22 May 2026
- Respighi BidCo, revised price, agreements and timetable, 6 October 2026
- Respighi BidCo, offer document, sections A.1.2, D.1 and E.5, 20 July 2026
- Borsa Italiana, Teleborsa acceptance bulletin, 7 October 2026, 18:00
- Teleborsa via La Repubblica, acceptance bulletin, 8 October 2026, 18:45
- Borsa Italiana, Teleborsa acceptance bulletin, 5 October 2026
- Borsa Italiana, Teleborsa acceptance bulletin, 16 September 2026
Sources
- Respighi : apports, actions physiques et TRS au 12 octobre · Recordati / Respighi BidCo · Oct 12, 2026
- Recordati : apports au 8 octobre 2026 · Teleborsa via La Repubblica · Oct 8, 2026
- Recordati : avis du conseil sur le prix révisé · Recordati / Respighi BidCo · Oct 7, 2026
- Respighi : prix relevé à 53 euros et calendrier · Recordati / Respighi BidCo · Oct 6, 2026
- GBL announces offer for Recordati · GBL · May 22, 2026
- Respighi BidCo : prix relevé, accords modifiés et calendrier · Respighi BidCo · Oct 6, 2026
- Recordati : apports au 12 octobre, 50,39 % des titres visés · Teleborsa · Oct 12, 2026
Share this article